When investing in mutual funds, one of the most common questions is whether to choose a Systematic Investment Plan (SIP) or make a Lump Sum Investment. Both methods can help you build wealth, but they work differently and are suitable for different financial situations. Your choice depends on factors such as your income, available funds, investment goals, and risk tolerance. This guide compares SIP and lump sum investments to help you decide which option may be right for you.
Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing.
Quick Highlights
| Feature | SIP | Lump Sum |
| Investment Method | Regular fixed investments | One-time investment |
| Best For | Salaried individuals and beginners | Investors with a large amount available |
| Market Timing Risk | Lower due to staggered investments | Higher, as the entire amount is invested at once |
| Investment Discipline | High | Depends on the investor |
| Minimum Investment | Often starts from ₹100–₹500 | Varies by mutual fund |
What Is SIP?
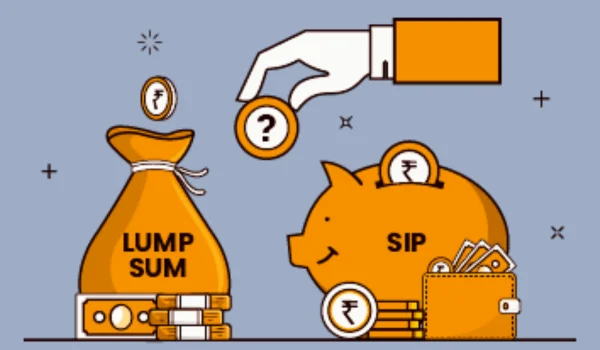
A Systematic Investment Plan (SIP) allows you to invest a fixed amount at regular intervals, such as monthly or quarterly, in a mutual fund.
Example:
- ₹500 every month
- ₹2,000 every month
- ₹5,000 every month
The amount is automatically invested on the selected date.
What Is Lump Sum Investment?
A lump sum investment means investing a large amount in a mutual fund in a single transaction.
Example:
- ₹50,000
- ₹1 lakh
- ₹5 lakh
The entire amount starts participating in the market immediately.
SIP vs Lump Sum: Key Differences
| Feature | SIP | Lump Sum |
| Investment Frequency | Regular | One-time |
| Initial Investment | Small | Large |
| Market Timing Risk | Lower | Higher |
| Rupee Cost Averaging | Yes | No |
| Suitable for Salaried People | Yes | Not always |
| Suitable for Bonus or Windfall Money | Limited | Yes |
| Investment Discipline | Automatic | Self-managed |
How SIP Works
With SIP:
- A fixed amount is invested regularly.
- You buy more units when prices are lower.
- You buy fewer units when prices are higher.
This concept is known as rupee cost averaging, which helps reduce the impact of market volatility over time.
How Lump Sum Works
In a lump sum investment:
- The entire amount is invested on one date.
- Returns depend heavily on market conditions after the investment.
- If markets rise over time, returns may be attractive.
- If markets decline soon after investing, the portfolio value may temporarily fall.
Benefits of SIP
Affordable
You can start investing with a relatively small amount.
Disciplined Investing
Regular contributions encourage long-term investing habits.
Lower Market Timing Risk
Since investments are spread over time, you don’t need to predict the “perfect” time to invest.
Ideal for Monthly Income
SIP is well suited for salaried employees and anyone with regular income.
Benefits of Lump Sum Investment
Full Amount Invested Immediately
Your entire capital starts participating in the market from day one.
Suitable for Windfall Gains
Ideal if you receive:
- Annual bonus
- Inheritance
- Sale proceeds from property
- Business profits
Simpler to Manage
Only one investment transaction is required.
When Should You Choose SIP?
SIP may be suitable if:
- You receive a monthly salary.
- You’re a beginner.
- You prefer gradual investing.
- You want to build long-term wealth.
- You don’t have a large amount available.
When Should You Choose Lump Sum?
Lump sum investing may be suitable if:
- You already have a significant amount to invest.
- You have a long investment horizon.
- You’re comfortable with market fluctuations.
- Your financial plan supports investing the amount immediately.
Which Option Gives Better Returns?
Neither SIP nor lump sum is always better.
It depends on:
- Market conditions
- Investment duration
- Mutual fund performance
- Timing of the lump sum investment
- Consistency of SIP contributions
For example:
- During a steadily rising market, a lump sum investment may outperform because the entire amount is invested earlier.
- During volatile or falling markets, SIPs may benefit from rupee cost averaging.
Long-term outcomes depend on many factors, and past performance does not guarantee future returns.
Can You Use Both?
Yes.
Many investors combine both approaches.
For example:
- Invest monthly through SIP.
- Invest annual bonuses or other surplus funds as lump sum investments.
This strategy can help balance regular investing with efficient use of extra funds.
Common Mistakes to Avoid
- Stopping SIPs during temporary market declines
- Investing a large lump sum without considering your financial goals
- Expecting guaranteed returns
- Choosing funds based only on recent performance
- Ignoring asset allocation
Tips for Investors
- Invest according to your financial goals.
- Stay invested for the long term.
- Review your portfolio periodically.
- Increase SIP contributions as your income grows.
- Avoid making investment decisions based on short-term market movements.
Frequently Asked Questions
Which is better: SIP or lump sum?
Neither is universally better. SIP is often preferred for regular investors, while lump sum may suit those with a large amount available for long-term investment.
Can I start a SIP with ₹500?
Yes. Many mutual funds allow SIPs starting from ₹100 to ₹500, though minimum amounts vary by scheme.
Is SIP risk-free?
No. SIP is a method of investing, not an investment product. The value of your investment depends on the performance of the underlying mutual fund.
Can I convert a lump sum investment into a SIP?
A lump sum investment and a SIP are different investment methods. However, you can make a lump sum investment and also start a SIP in the same or another mutual fund if it suits your financial plan.
Can I stop my SIP anytime?
Yes. Most mutual funds allow investors to pause or stop SIPs, subject to the terms of the investment platform or fund.
SIP vs Lump Sum at a Glance
| Factor | SIP | Lump Sum |
| Best For | Beginners and salaried individuals | Investors with surplus funds |
| Investment Style | Regular | One-time |
| Market Timing Risk | Lower | Higher |
| Investment Amount | Small and regular | Large |
| Rupee Cost Averaging | ✔ | ✘ |
| Long-Term Wealth Creation | ✔ | ✔ |
Conclusion
Both SIP and lump sum investments are effective ways to invest in mutual funds, but the right choice depends on your financial situation and goals. SIPs are ideal for investors who want to invest regularly, reduce market timing risk, and build disciplined investing habits. Lump sum investments can be suitable when you have a significant amount available and a long-term investment horizon. Rather than focusing on which method is universally better, choose the approach—or a combination of both—that aligns with your income, risk tolerance, and long-term financial objectives.